
1. The Startup Offer Trap: Decoupling Nominal Valuation from Realized Net Worth
When an offer letter outlines $185,000 in base salary alongside $200,000 in stock options vesting over four years, the intuitive reaction is to calculate your total target annual compensation at $235,000.
In personal finance, this mental accounting is often disastrous.
Unlike publicly traded equity (such as Apple or Microsoft RSUs), private company stock is an illiquid, subordinate financial derivative. You cannot pay your mortgage with non-transferable option grants, nor can you tender private equity during an unforeseen liquidity crunch.
To convert paper wealth into an actual financial plan, you must calculate its Risk-Adjusted Expected Value (EVEVEV).
Expected Value (EV)=[(Target Exit Value−Strike Price)×Shares]×P(Exit)×(1−Cumulative Dilution)×(1−Effective Tax Burden)\text{Expected Value (EV)} = \left[ (\text{Target Exit Value} - \text{Strike Price}) \times \text{Shares} \right] \times P(\text{Exit}) \times (1 - \text{Cumulative Dilution}) \times (1 - \text{Effective Tax Burden})Expected Value (EV)=[(Target Exit Value−Strike Price)×Shares]×P(Exit)×(1−Cumulative Dilution)×(1−Effective Tax Burden)
According to historical benchmark datasets from AngelList and Carta, fewer than 14% of seed-funded and 28% of Series B startups reach an IPO or accretive M&A exit. Without a framework to haircut nominal grants, candidates regularly trade off $40,000 to $80,000 in guaranteed annual salary for equity worth zero.
2. ISOs vs. NSOs vs. RSUs: Structural & Tax Differences
Understanding your legal grant type determines your upfront capital requirement, tax liability, and risk exposure.
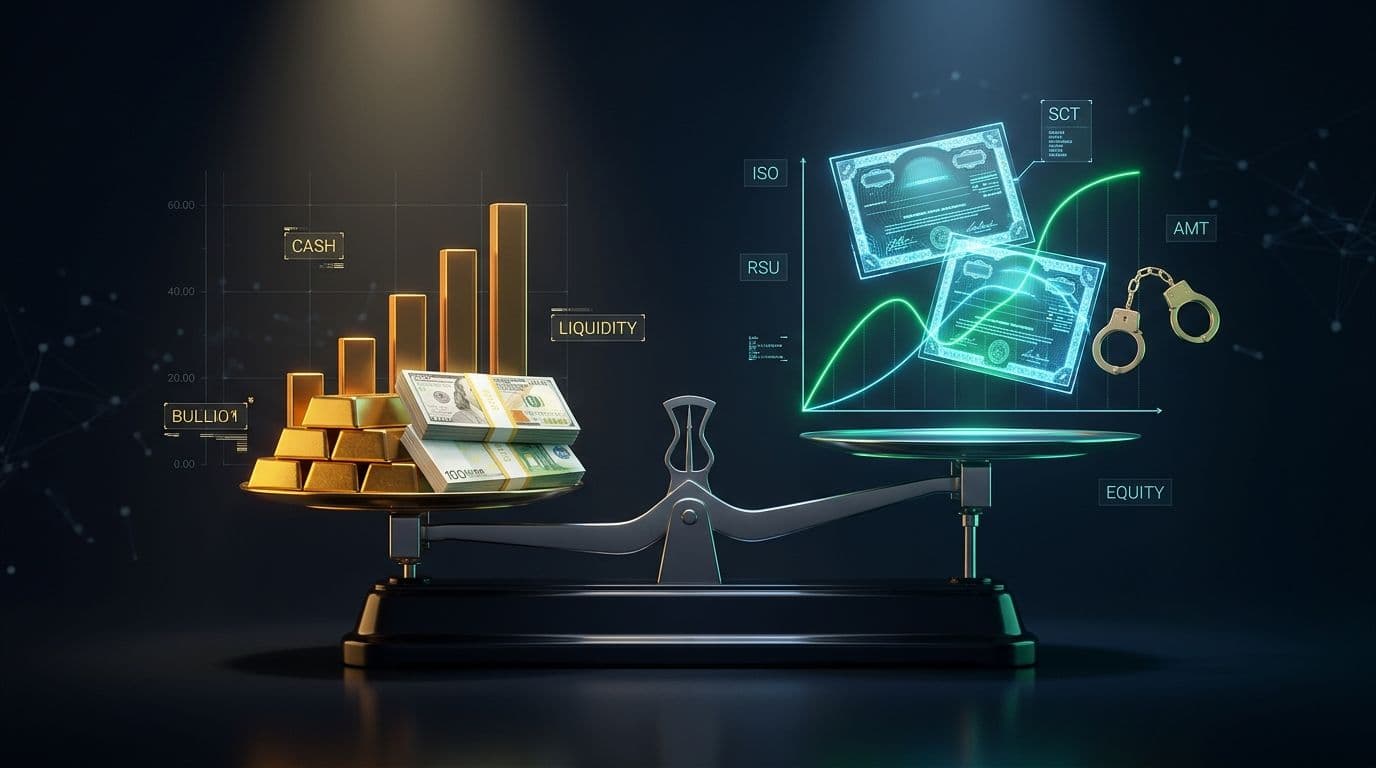
Summary Comparison Matrix & Venn Architecture
The following interactive graphic breaks down how stock grants intersect across tax events, liquidity timing, and capital risk:
Equity Archetypes: Risk vs. Tax Venn Diagram
Visualizing the critical friction points between upfront capital outlay, phantom income, and liquidity timing.
ISOs High Tax Leverage
Incentive Stock Options available only to employees. Potential for zero ordinary income tax on sale.
- Cost to Exercise: Cash out-of-pocket required.
- Tax Trap: Triggers AMT (Form 6251) on paper spread.
- Capital Gains: Eligible for LTCG if held 1 yr past exercise & 2 yrs past grant.
Non-Qualified Stock Options granted to contractors, advisors, and employees.
- Cost to Exercise: Cash out-of-pocket required.
- Immediate Tax: Spread taxed as ordinary income upon exercise.
- Withholding: Requires employer FICA/W-2 withholding upon exercise.
Restricted Stock Units issued by late-stage or publicly traded corporations.
- Cost to Exercise: $0 out-of-pocket required.
- Immediate Tax: Taxed as ordinary W-2 income upon vesting date.
- Double-Trigger: Private RSUs require both time vest and liquidity event.
Key Rule: Options grant the right to buy shares at a predetermined strike price; RSUs are actual stock units delivered without an exercise price.
3. The Phantom Wealth Hazard: Understanding Alternative Minimum Tax (AMT)
The single greatest financial trap for startup employees holding Incentive Stock Options is the Alternative Minimum Tax (AMT) spread.
How AMT Derails Personal Liquidity
When you exercise an ISO, the difference between your strike price and the current Fair Market Value (FMV) established by the company's 409A appraisal is considered preference income for AMT purposes (IRC §56(b)(3)).
A Real-World Exercise Scenario:
- Granted: 50,000 ISOs at a strike price of $1.00/share.
- Current 409A Valuation (Series C): $11.00/share.
- Cost to Exercise: $50,000 ($1.00 × 50,000).
- Paper Spread: $500,000 [($11.00 - $1.00) × 50,000].
Even though you have received zero dollars in liquid cash, the IRS treats this $500,000 spread as income under AMT calculations. Depending on your filing status, your resulting federal AMT tax bill can exceed $130,000, due on April 15th of the following tax year.
If the startup subsequently enters a down-round, stagnates, or shuts down, you cannot retroactively refund the AMT paid. You have paid six figures in hard cash for equity that has become worthless.
4. The Equity Decision Waterfall: A Step-by-Step Strategic Framework
Before accepting an offer or writing an exercise check, execute this five-stage evaluation protocol:
The 5-Stage Compensation Verification Protocol
1. Establish Fully Diluted Percentage:
Never settle for raw share counts (e.g., "50,000 shares"). Request the exact percentage ownership on a fully diluted basis, including unallocated option pools and convertible notes.
2. Analyse the Liquidation Preference Stack:
Common stockholders are paid last. In the event of an acquisition below the total preferred capital raised, common shareholders receive $0 regardless of stated ownership.
3. Calculate Exercise Capital Reserves:
Calculate: Never commit more than 10%–15% of your total liquid net worth to unexercised private options.
4 Check for Early Exercise & 83(b) Provisions:
If joining at pre-seed or Series A, verify if the plan permits early exercise of unvested options. Exercising when FMV equals strike price creates $0 AMT liability and starts the 1-year long-term capital gains clock immediately.
5 Stress-Test Against Guaranteed Cash:
Take the salary delta offered by mature corporate employers and run it through our Compound Interest Engine at an 8% index fund baseline. If the startup's risk-adjusted EV fails to outpace compound savings, prioritise cash.
5. How to Value Public RSUs vs. Private Startup Equity
If you are choosing between an established technology enterprise (e.g., Alphabet, Amazon, Nvidia) and a Series B startup, the decision framework shifts from valuation modelling to concentration risk management:
- Public RSUs are Guaranteed Cash Equivalents: Because public shares can be immediately liquidated upon vest, treat RSUs as cash compensation with automatic market exposure during vesting intervals.
- The Single-Stock Bias: Many tech professionals let vested RSUs accumulate, inadvertently tying their employment, health insurance, and 70%+ of their liquid portfolio to a single corporate entity.
- The Same-Day Sale Rule: Best-practice wealth management dictates selling public RSUs immediately upon vesting and redeploying the proceeds into diversified broad-market ETFs (e.g., S&P 500 or Total World Stock Index). There is no tax penalty for selling on vesting day because the value has already been taxed as ordinary income.
6. Mathematical Case Study: The True Cost of a $50k Salary Trade-Off
Consider two competing job offers for a senior software architect:
- Offer A (Public Tech Firm): 210,000 base salary + 210,000 base salary + 210,000 base salary + 80,000 annual public RSUs = $290,000 total compensation.
- Offer B (Series B Startup): 160,000 base salary + 0.25160,000 base salary + 0.25% equity grant (valued at 160,000 base salary + 0.25100,000/yr on paper) = $260,000 nominal compensation.
4-Year Compounding Model Analysis
Over 4 years, Offer A guarantees $200,000 more in cumulative base salary.
If invested in a standard diversified portfolio compounding at an annualised 7.5% real return, that $50,000 annual cash delta grows to ~$241,000 in liquid capital at the end of the vesting cycle.
For Offer B's equity grant to yield an equivalent after-tax sum, the startup must exit at a minimum valuation of $180 Million, assuming a standard 25% cumulative dilution across subsequent Series C and Series D funding rounds.
Before taking Offer B, the candidate must answer: Does this venture realistically possess a credible path to a $200M+ liquidity event, or am I underwriting the founders' risk with my personal balance sheet?
This article is published strictly for educational and informational purposes and does not constitute individual legal, tax, or investment advice. Tax laws, state marginal brackets, and corporate securities regulations are subject to frequent legislative amendments. Consult a qualified Certified Public Accountant (CPA) and fee-only financial planner before executing stock option exercises or tax elections.